
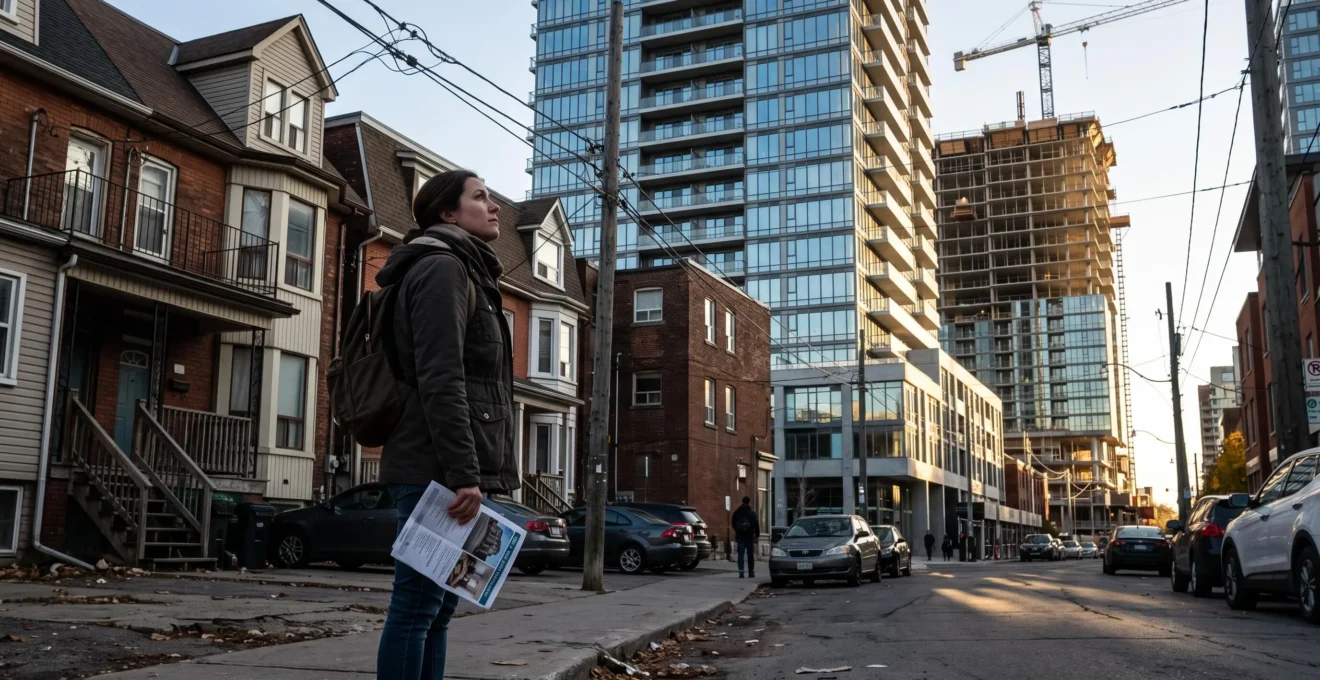
A new residential tower begins rising on your corner. The developer announces international institutional financing, neighborhood businesses evolve, and nearby asking prices start climbing. Should you anticipate an immediate 8% surge in local home prices?
Not necessarily. Inbound foreign investment can capitalize new construction, stimulate regional economic activity, and expand total housing supply. However, it can also intensify competition for specific property segments, particularly when investor capital targets neighborhoods where available inventory remains severely constrained.
The 8% figure is neither a reliable forecast nor a proven average effect across Canada. Available empirical data does not support attributing a fixed price increase to the international origin of development financing. To understand shifts in your community, you must distinguish between foreign capital financing new housing construction, capital acquiring existing residential properties, and concurrent shifts in domestic consumer demand.
Foreign Investment and Real Estate Prices: Key Takeaways
- Foreign capital can expand future housing inventory while temporarily intensifying competition within specific market segments.
- Non-resident ownership, residential vacancy, and corporate property holding are three distinct concepts: none, on its own, proves upward price pressure.
- When deciding whether to buy or wait, recent comparable sales, actual building completions, and personal borrowing capacity are far more reliable than alarming percentage headlines.
- Why foreign capital can expand housing supply while driving up prices in specific areas
- How to identify external capital inflows in your area using 3 public indicators
- Why a “housing shortage” persists even with 3 active construction sites on your street
- Purpose-built rentals vs. condominiums: Which expands supply faster as interest rates rise?
- New construction vs. resale: Where foreign investment impacts local buyers the most
- The mistake skewing public debate: Confusing “jobs created” with “homes left vacant”
- How to interpret immigration statistics without conflating permanent and temporary residents
- When to buy if your area is heating up: 4 steps to decide without FOMO
Why foreign capital can expand housing supply while driving up prices in specific areas
Foreign capital can accelerate housing construction while simultaneously intensifying market competition. The net impact depends on deployment: financing the development of a purpose-built rental building yields fundamentally different outcomes than acquiring existing freehold or condominium homes. Local impacts vary based on neighborhood inventory, construction timelines, prevailing interest rates, and organic demographic demand.
When a real estate developer secures international equity or debt financing to erect a residential high-rise, it mobilizes capital that allows new housing units to break ground. Over the long term, these completed units expand aggregate residential supply. However, that supply only benefits the community once construction finishes, occupancy permits are issued, and units are placed on the market.
Conversely, when an investor acquires an existing residential property, the overall housing stock remains unchanged. The transaction merely transfers ownership from one party to another. If multiple domestic and international buyers compete for a limited pool of existing homes, competitive bidding drives up market values, regardless of buyer residency.
The critical distinction lies in net supply addition. Newly built residential buildings add net physical capacity to the market. Purchasing an existing home creates no new housing capacity on its own.
Rental and homeownership markets also respond differently. A high-density purpose-built rental tower expands options for local tenants, whereas luxury condominiums in high-demand urban centers provide little relief for middle-income buyers seeking starter homes.
Geography plays an equally decisive role. Two adjacent neighborhoods can experience divergent price trends due to differing transit access, housing typology, median household incomes, or historical permitting paces. A local price increase alone does not prove the causal impact of foreign capital.
Hypothetical Scenario: Two Neighborhoods, Two Trajectories
In Neighborhood A, an international institutional fund finances a mid-rise purpose-built rental building whose units will enter the local rental pool upon completion. In Neighborhood B, external investors purchase existing resale condominiums in a sector where comparable properties are scarce.
The first investment can gradually alleviate local rental pressures by delivering new units. The second intensifies direct buyer competition, supporting upward price pressure on resale units. Both outcomes remain contingent: final rents and home prices will still depend on local job growth, mortgage rates, and broader housing completions.
Regarding the 8% figure cited in casual market commentary, econometric studies do not provide a causal baseline establishing this as a standardized Canadian outcome. It should be evaluated as an illustrative planning scenario rather than an established empirical rule. Observed home price movements are driven primarily by mortgage qualifying rates, household income growth, municipal zoning constraints, and macro housing cycles.
Before attributing local price inflation to foreign development capital, determine what type of housing is actually being funded, when units will reach completion, and which demographic segment they will serve.
How to identify external capital inflows in your area using 3 public indicators
Three public indicators can help assess external investment in a neighborhood: the proportion of non-resident ownership, residential occupancy and vacancy data, and corporate or trust ownership metrics on municipal property rolls. These data points must be cross-referenced with local transactions and understood within their statistical limits, as no single metric directly isolates foreign capital sources.
The primary baseline is the Canadian Housing Statistics Program (CHSP) administered by Statistics Canada. The program cross-references residential property title records with tax filer data to determine owner residency status.
Release data from August 26, 2026, provides non-resident ownership metrics for Calgary and Edmonton for the 2024 reference year. The agency cautions that methodology refinements between 2023 and 2024 can influence comparative percentages. Notably, the CHSP dataset excludes residential properties situated in Quebec and on First Nations reserve lands.
Statistics Canada’s Canadian Housing Statistics Program data allows researchers to examine available tables and verify geographic coverage before drawing comparative conclusions.
To use this data effectively, identify your census metropolitan area (CMA), select matching reference years, and examine category definitions carefully. A metropolitan-wide non-resident ownership rate cannot simply be extrapolated to a specific postal code or street block.
The second indicator is occupancy status. Statistics distinguish between owner-occupied dwellings and tenant-occupied or secondary properties, while several municipalities maintain mandatory vacant home tax registries. However, a property not occupied by its registered owner is not necessarily empty: it is often leased to long-term tenants as primary housing.
The third indicator involves corporate and trust ownership. Depending on the province, municipal property assessment rolls and land registry databases document whether title is held by an individual, corporation, or numbered company. However, land titles do not always disclose the underlying beneficial ownership or the debt financing structure behind the holding entity.
Canada does not maintain a single, consolidated public registry that tracks every foreign capital stream behind private real estate acquisitions. Disclosure requirements, registry access policies, and data depth vary across provincial jurisdictions.
The table below summarizes how to interpret these public indicators without overstating their diagnostic reach:
| Public Indicator | What It Measures | What It Does Not Prove |
|---|---|---|
| Non-resident property ownership | Proportion of properties owned by individuals residing outside Canada | Physical unit vacancy or speculative market behavior |
| Occupancy and vacancy declarations | Tenure status of residential stock according to municipal filings | Foreign citizenship or international capital source |
| Corporate and trust title holdings | Properties titled to legal entities rather than private individuals | Foreign institutional funding or lack of resident tenants |
Even when analyzed together, these indicators serve as preliminary signals rather than definitive proof of external market distortion. Assessing neighborhood pricing requires evaluating closed comparable sales, months of inventory, vacancy rates, and new building delivery paces.
This structured analysis prevents conflating distinct realities: corporate title ownership, physically vacant apartments, and international investment capital represent three entirely different conditions.
Why a “housing shortage” persists even with 3 active construction sites on your street
Seeing three active construction cranes down the street does not mean new housing is immediately available for local residents. Significant time elapses between initial excavation, building completion, and final occupancy permits. In regions carrying deep structural housing deficits, newly delivered units are often absorbed almost instantly.
Housing market statistics track three sequential phases: housing starts (groundbreaking), completions (construction finished), and absorptions (units leased or sold to occupants). This distinction explains why neighborhood residents can see cranes everywhere while local rents and home prices continue to rise.
A tower under construction cannot house residents today. Even upon receiving occupancy permits, many pre-construction condominium units were sold years earlier to buyers or investors. While completions expand the aggregate housing stock, they do not trigger immediate drops in prevailing asking prices.
Canada faces an underlying housing deficit that far exceeds current building activity.
430,000 to 480,000 homes per year
The annual national construction pace CMHC estimated as necessary over the decade following June 2025 to restore housing affordability to 2019 levels. This represents an estimated supply requirement, not actual construction output.
CMHC news release on residential housing supply needs, June 2025
Housing requirements vary significantly by metropolitan area. In its modeling, CMHC estimated that a 70% increase in homebuilding over a decade would be required to restore affordability benchmarks in Toronto. For Vancouver, the agency projected an annual requirement of 7,200 additional housing units above baseline status-quo projections.
These projections underscore the challenge of historical deficits: accelerating construction today cannot instantly neutralize years of lagging home supply. Household growth, demographic shifts, and the specific composition of housing being built remain decisive.
Absorption velocity is a critical market indicator. When newly completed units are absorbed immediately, added supply stabilizes market pressure without causing asking rents to drop. Conversely, a prolonged accumulation of unabsorbed inventory increases tenant and buyer bargaining power.
Housing typology matters just as much as unit counts. Delivering high-priced studio condominiums does not directly alleviate shortages for families needing multi-bedroom rental apartments or middle-income buyers seeking starter homes.
The next analytical step is evaluating which housing types remain financially viable to build as macroeconomic credit conditions tighten.
Purpose-built rentals vs. condominiums: Which expands supply faster as interest rates rise?
When interest rates climb, condominium projects that rely on pre-construction sales become vulnerable to financing delays. In response, some residential developers pivot toward purpose-built rental buildings. However, purpose-built rental construction is not immune to economic downturns: both development models face elevated borrowing costs, labor shortages, and strict profitability thresholds.
The operational difference stems from their financing structures. Condominium developments depend on pre-construction sales to secure construction financing from lenders. When interest rate hikes erode buyer borrowing power, investor pre-sales and end-user demand can slow dramatically.
CMHC documented this vulnerability in a market analysis of Toronto and Vancouver published in June 2025. In the first quarter of 2025, 55 % of pre-construction condominium units in Toronto were unsold. Furthermore, in 2024, condominium project cancellations rose to five times 2022 levels in Toronto and ten times in Vancouver.
According to CMHC report on condominium apartment market risks in Toronto and Vancouver, developers increasingly turned toward rental development to navigate difficult condominium financing markets.
Purpose-built rental developments held by institutional pension funds or real estate investment trusts (REITs) are underwritten against long-term rental income yields rather than upfront individual sales. They operate on different financial timelines. Nonetheless, high interest rates increase debt-service carrying costs for rental projects as well, occasionally forcing project pauses.
The table below summarizes the economic profiles of both development models:
| Evaluation Dimension | New Condominiums | Purpose-Built Rentals |
|---|---|---|
| Financing Mechanism | Pre-construction deposits and developer credit facilities | Long-term institutional equity, commercial mortgages, and rental yields |
| Rate Sensitivity | Consumer mortgage qualification and developer loan rates | Capitalization rates, commercial borrowing costs, and projected rent growth |
| Primary Delivery Risk | Insufficient pre-sale absorption, construction delays, or cancellations | Lower operational yields, debt refinancing hurdles, or construction cost overruns |
| Impact on Market Supply | Expands stock of units available for private purchase | Expands dedicated long-term tenant housing stock |
For prospective homebuyers, a shift toward rental development alters local inventory dynamics. A surge in purpose-built rental construction improves tenant options, but does not add inventory to the homeownership market.
It is also essential to separate project-level development financing from individual unit acquisitions. The federal Prohibition on the Purchase of Residential Property by Non-Canadians Act, extended through January 1, 2027, governs residential acquisitions by non-Canadians under specific statutory definitions and exemptions, supplemented by provincial non-resident speculation taxes. It does not prohibit international institutional capital from funding multi-unit residential construction in Canada.
Prospective buyers must focus on the actual housing product being completed, rather than headline investment figures or building permit counts.
New construction vs. resale: Where foreign investment impacts local buyers the most
In the pre-construction market, external capital influences construction financing, project viability, and unit releases. In the resale market, qualified buyers compete directly for completed, existing homes. Neither sector is universally more exposed: statutory frameworks, local supply constraints, and investor objectives dictate actual market pressure.
In new developments, an investor purchasing a pre-construction condominium helps the builder reach the pre-sale thresholds required to secure construction loans. However, that transaction absorbs an allocation of units, leaving fewer pre-sale choices for end-user purchasers.
This dynamic creates a two-sided effect: it facilitates the financing required to add new housing supply, while simultaneously absorbing units during initial launch phases.
When real estate markets cool, some buyers utilize contract assignments, where permitted by the purchase agreement. The original purchaser assigns their contractual rights to a new buyer prior to building completion and final title transfer. Assignment markets can present buying opportunities, but carry specific legal, financing, and tax complexities.
The existing resale market functions differently. Here, eligible purchasers compete for completed homes ready for immediate occupancy. Market pricing is driven by inventory levels, buyer financing, and neighborhood sales volume. Attributing bidding competition solely to foreign capital without verifying buyer profiles overlooks broad domestic market forces.
Statutory regulations restrict residential acquisitions. In February 2024, the federal government extended the ban on non-Canadian purchases of residential property through January 1, 2027. The scope of this restriction depends on property classification, municipality, buyer residency status, and statutory exemptions.
Provincial foreign-buyer taxes and assignment reporting rules also apply across several jurisdictions. The Department of Finance Canada news release on the extension of the ban on foreign buyers outlines policy intent, but buyers must review governing legislative texts and seek professional legal advice for specific transactions.
Local buyers evaluating pre-construction should review builder track records, contract disclosure statements, estimated closing adjustments, and assignment restrictions. For existing resale properties, buyers should analyze comparable neighborhood sales, condo corporation reserve fund studies, and maintenance records.
While the overall percentage of investor-owned properties in a building is an important operational metric, it cannot be deduced simply by counting the number of tenant-occupied units.
The goal is not to avoid developments funded by institutional capital, but to purchase a home whose pricing, closing costs, and legal terms match your financial position.
The mistake skewing public debate: Confusing “jobs created” with “homes left vacant”
Construction employment and residential vacancy reflect two completely separate economic realities. A real estate development can generate local construction jobs without significantly improving housing access for local residents. Conversely, a development backed by international capital can create construction employment while adding fully occupied long-term housing. Economic activity and residential utilization must be evaluated independently.
Residential construction employs skilled trades, general contractors, engineers, and suppliers. These activities support regional economic growth during development, followed by ongoing employment in property management and building maintenance.
However, construction job creation reveals nothing about how completed homes are occupied. To evaluate a development’s true housing contribution, you must examine how many units are occupied as primary residences, how many enter the long-term rental market, and whether units sit persistently unoccupied.
Data measurement adds another layer of complexity. Statistical programs apply precise definitions to owner residency, residential use, and occupancy status. Municipal tax filings, census datasets, and administrative property rolls do not measure identical phenomena.
The distinction between non-resident ownership and physical home vacancy is vital. An individual residing outside Canada may own a condominium that is leased year-round to a local resident. Conversely, a Canadian citizen may own a secondary property that sits unoccupied for months.
Data from the Canadian Housing Statistics Program shows that refinements in tax record linkage can adjust reported non-resident ownership percentages over time. Statistical adjustments reflect enhanced data matching rather than sudden shifts in homeowner behavior.
Two hypothetical examples illustrate the contrast: In the first, an institutional developer builds an apartment tower that achieves rapid full occupancy. The project creates construction jobs and expands local rental supply. In the second, high-end condominium units are acquired as secondary residences and remain largely unoccupied. Economic activity occurred during construction, but the development provides little relief to local housing demand.
These scenarios do not represent macro market averages; they illustrate why the origin of investment capital does not dictate its ultimate housing impact.
Municipalities utilize planning policies, density bonuses, and vacant home taxes to encourage full residential utilization. The efficacy of these policy tools must be measured using verified tax filings and market data.
When assessing a local project, evaluate two distinct questions: Does the development provide sustainable economic activity, and what volume of functional, accessible housing does it deliver to the neighborhood? The answers can be positive on one count and neutral or negative on the other.
This distinction becomes even more critical when local housing discussions blur development capital, population growth, and immigration—three distinct forces with differing impacts on real estate.
How to interpret immigration statistics without conflating permanent and temporary residents
To analyze the relationship between immigration and real estate, you must distinguish between permanent resident admissions and temporary permit holders. Both groups require shelter, but their legal status, duration of stay, purchasing eligibility, and housing preferences differ. Headline immigration figures must be evaluated alongside departures, status transitions, and net housing completions.
Permanent residents hold long-term rights to reside in Canada. They participate in both rental and homeownership markets based on household income, savings, family size, and settlement location.
Temporary residents include international students and temporary foreign workers. Their demand is concentrated heavily in the rental market, often near post-secondary institutions or major employment hubs. However, assuming that all temporary residents seek identical housing formats is an inaccurate oversimplification.
A common mistake in housing commentary is double-counting immigration statistics. Aggregating new admissions, temporary visa holders, permit renewals, and status transitions does not equal that exact number of new households requiring new housing units.
A legal change in immigration status does not automatically mean a new household has entered the housing market. An individual transitioning from an open work permit to permanent residency is already living in Canada and often remains in their existing apartment.
While the federal Immigration Levels Plan targets established by Immigration, Refugees and Citizenship Canada (IRCC) provide national context, national targets alone cannot forecast neighborhood-level rental trends.
National figures must be contextualized by the regional settlement patterns of newcomers, demographic trends among existing residents, average household size, and local housing completions. Emigration and interprovincial migration also reshape housing demand.
A metropolitan area experiencing population growth alongside weak housing completions will see heightened rental pressure, even without foreign capital inflows. Conversely, strong housing delivery or slower household formation can ease market competition.
Federal policy adjustments alter future intake targets, particularly for non-permanent residents. However, announced immigration targets represent policy objectives rather than precise forecasts of net housing absorption on a specific urban street.
To avoid flawed conclusions, evaluate demographic data across consistent timeframes, distinct residency categories, and specific metropolitan boundaries. A national immigration headline cannot explain localized price movements in a specific borough.
While demographic trends help clarify broad housing dynamics, they do not dictate whether you should buy today. Your personal decision should rest on localized property data and your capacity to manage diverse financial scenarios.
Key Considerations Before Making a Real Estate Decision
- Rising asking prices do not prove a neighborhood will experience permanent capital appreciation: closed transactions and days on market provide far better context.
- Significant external development investment can coincide with a broader housing market slowdown. Project viability and local purchasing power remain paramount.
- The right decision depends first on your personal budget, family living needs, and your capacity to hold the property through adverse market conditions.
When to buy if your area is heating up: 4 steps to decide without FOMO
When capital investment accelerates in your neighborhood, the best time to buy is not necessarily when asking prices appear to be surging. It is far safer to verify closed comparable sales, stress-test your finances, define your ownership timeline, and model a potential market correction. This disciplined approach prevents overpaying out of fear of missing out (FOMO).
FOMO can lead buyers to view every construction crane as proof that home prices will rise indefinitely. However, high-demand neighborhoods can easily undergo price corrections or extended plateaus if borrowing rates rise or supply surges.
Step 1 — Objectify market trends. Examine closed transaction prices for comparable properties rather than advertised list prices. Where MLS data is accessible, analyze average days on market (DOM), the percentage of homes selling above asking, and the relationship between purchase prices and local rents.
A high price-to-rent ratio does not automatically indicate an asset bubble, but it warrants testing future appreciation assumptions and rental yield realities.
Step 2 — Stress-test your monthly cash flow. Construct a budget that includes stress-tested mortgage payments, condo fees, municipal property taxes, insurance, routine maintenance, and transaction costs. Model your cash flow under higher interest rate scenarios to verify you can absorb rising expenses or temporary income disruptions.
Budget for municipal land transfer taxes, legal fees, and moving expenses. For pre-construction purchases, review contract adjustments, utility connection levies, and occupancy fees thoroughly.
Step 3 — Weigh buying against waiting. Purchasing makes sense if your employment is stable, the property fits your functional living requirements, and you plan to hold the asset long enough to amortize transaction costs and ride out market cycles.
Continuing to rent is completely rational if your career path is shifting, your finances are stretched, or available homes do not meet your family’s needs. Waiting does not require you to forecast short-term market movements.
Step 4 — Model a downside scenario. Consider what happens if new housing completions increase inventory, average selling times lengthen, or pre-construction investors list assignment sales simultaneously. Determine whether you would remain financially secure holding the property under those conditions.
Transit access, neighborhood walkability, functional floor plans, and nearby schools retain lifestyle value regardless of market shifts or developer announcements.
Pre-Purchase Verification Checklist for Developing Neighborhoods
- Compile recent closed sales for comparable properties, recording sold prices, square footage, and days on market in a spreadsheet.
- Inventory active and planned residential developments in the area, noting planned units, expected completion dates, and tenure types (rental vs. condo).
- Compare prevailing rents for similar homes against target purchase carrying costs, documenting the price-to-rent ratio.
- Build a monthly carrying cost model incorporating condo fees, taxes, an interest rate buffer, and an emergency repair reserve.
- Write a one-page purchase mandate defining your firm price ceiling, intended holding period, and conditions under which you will walk away.
This process does not guarantee future market returns. However, it separates verifiable data from speculative market sentiment fueled by neighborhood hype or the origins of development capital.
Before submitting a purchase offer, benchmark your budget against closed sales data and verify all contract terms with licensed professionals. The goal is making a housing decision that remains financially sustainable, even if neighborhood price growth does not match optimistic projections.
Does a newly funded foreign development automatically increase neighboring home values?
No. Market impact depends on unit volume delivered, pricing tiers, local buyer demand, and completion timing. New construction expands residential inventory without automatically driving up surrounding home values. Available empirical research does not support an automatic 8% price increase.
Are non-Canadians legally permitted to purchase residential property in Canada?
A federal statute—the Prohibition on the Purchase of Residential Property by Non-Canadians Act—restricts non-Canadians from purchasing certain residential real estate, with the federal government extending this ban through January 1, 2027. The legislation contains specific definitions, criteria, and exemptions. Provincial non-resident taxes also apply across several jurisdictions. The Department of Finance Canada news release on the extension of the ban on foreign buyers outlines the policy, but buyers must review governing legislative texts and seek legal counsel.
Is an apartment building owned by an international corporation more expensive to rent?
Not necessarily. Rents are set by local supply, building amenities, operational expenses, and provincial residential tenancy regulations. Ownership structure alone does not dictate market rent. Tenants should compare similar rental units within the immediate neighborhood.
How can you distinguish actual market price increases from ambitious listing prices?
Focus strictly on closed sales data for comparable properties rather than advertised asking prices. Asking prices can be reduced during the marketing period and do not reflect final transacted values. Days on market, price reductions, and inventory absorption rates provide essential context.
Can public datasets track the exact share of foreign capital in a neighborhood?
Not exhaustively through public records alone. Non-resident ownership statistics track titleholders’ tax residency, which does not capture all international financing structures behind domestic corporate entities. Conversely, a non-resident owner may hold an apartment that is fully occupied by long-term local tenants. Data granularity varies across provincial and municipal land registries.